Market Intelligence
DRC & South Africa Minerals Brief: Cobalt Output Falls, Copper Rises and Trade Controls Tighten
Weekly intelligence on DRC copper and cobalt production, Musompo mineral-trading controls, lithium exploration delays, South African gold traceability and prices.
Published
Review period: 26 October–1 November 2026
By Afrimet Global Resources
This week at a glance
Review period: 26 October–1 November 2026
This week’s strongest developments were the DRC’s renewed formalisation of artisanal copper-cobalt sales, a sharp divergence between copper and cobalt output at Glencore’s Congolese operations, a procedural delay affecting KoBold Metals’ DRC lithium exploration, and a steep late-week gold correction.
These are market and operational signals. They are not evidence of new Afrimet supply, access or concluded partnerships. Each section below separates confirmed facts from Afrimet’s own analysis.
1. DRC — Musompo trading centre resumes weighing and assay; enforcement shifts
Confirmed facts — reported 27–28 October 2026
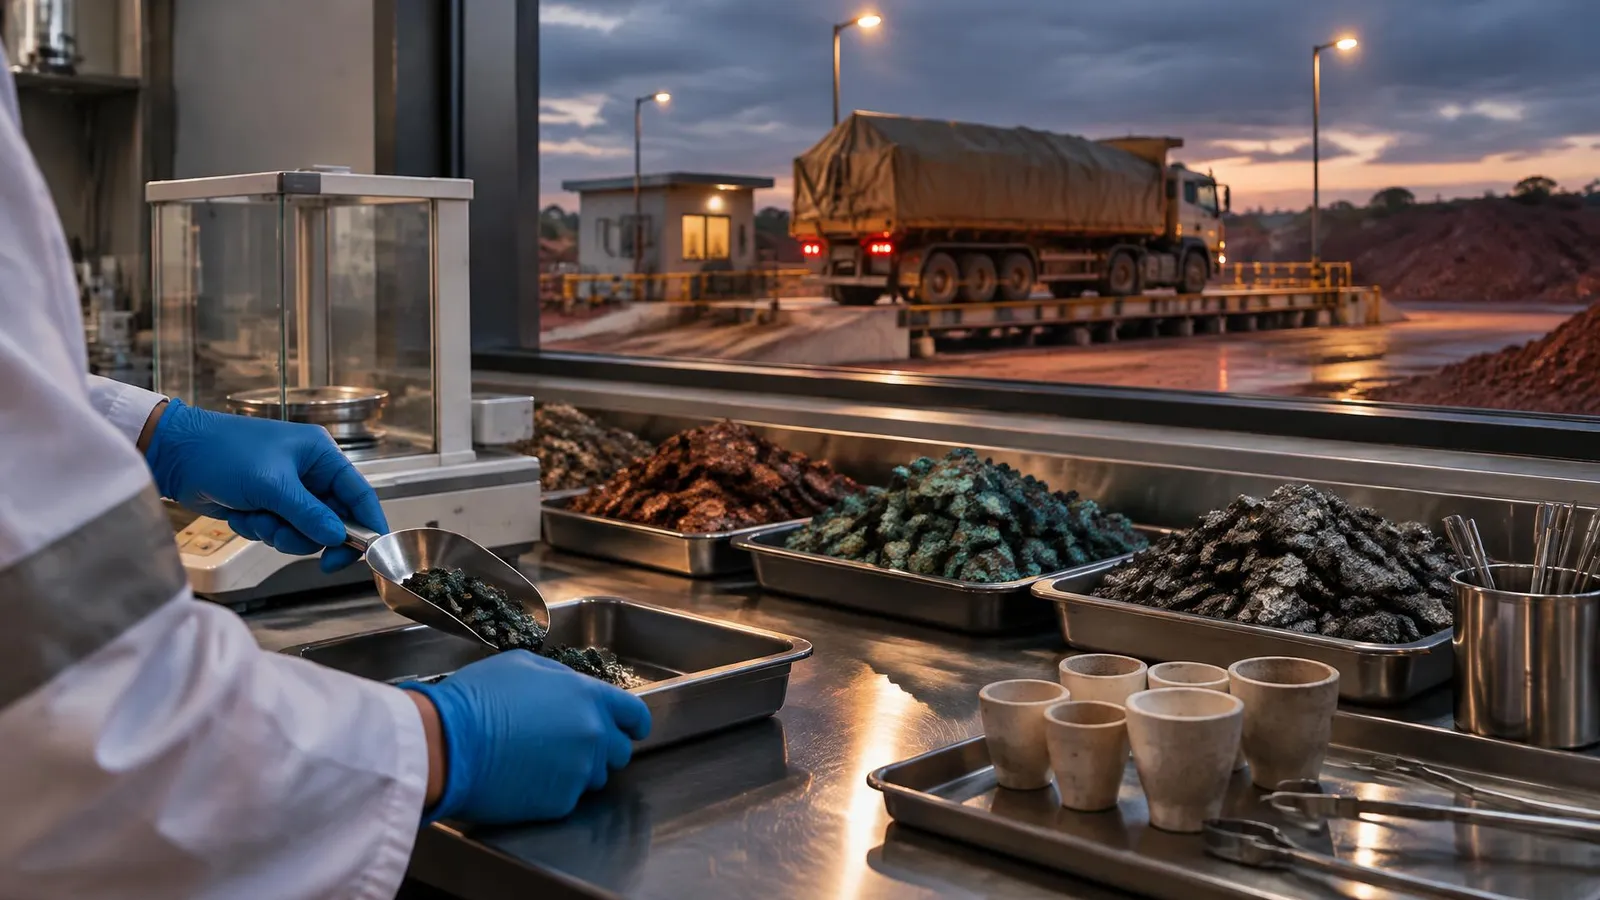
On 26 October 2026, Mines Minister Louis Watum Kabamba restarted activities at the Musompo mineral-trading centre near Kolwezi, Lualaba. Weighbridge operations resumed, together with sampling and mineral analysis by the Centre d’Évaluation, d’Expertise et de Certification (CEEC), and a first truck was weighed. The centre was inaugurated in October 2023 but had remained largely inactive.
Musompo has a nominal design capacity of 250 trucks a day, but technical difficulties mean it is not yet operating at full capacity. The restart followed protests by artisanal miners on 19–20 October over inspections and restricted sales channels, and local reporting says miners continue to complain about how and where they are allowed to sell.
Separately, Reuters reported on 27 October that the Mines Minister had suspended Jean-Paul Kadiobo Kapongo, director-general of SAEMAPE, the artisanal and small-scale mining agency, on 21 October. The order accused him of failing to prevent illegal artisanal mining on licensed concessions in Lualaba and Haut-Katanga, and of improperly setting up revenue-collection services inside concession areas. This is an administrative suspension based on allegations, not a court finding.
Afrimet implications (analysis/inference)
A working Musompo could create a more auditable route for eligible artisanal copper and cobalt material, with standardised weighing and assay helping to reduce disputes over quantity and grade. Operating capacity and trader access remain unproven, however, and protest and inspection friction could delay deliveries. Afrimet does not use Musompo and has no material there. Before considering any supply through this channel, Afrimet would verify:
- CEEC certificates and the eligibility of the source zone.
- Licensed trader and buyer status of every counterparty.
- Chain of custody, supported by weighbridge tickets.
- Moisture and dry-weight basis, sampling protocol and assay umpire arrangements.
- Applicable taxes and royalties.
2. DRC — copper up, cobalt sharply down at Glencore’s Congolese assets
Confirmed facts — Glencore report released 29 October 2026
Group figures (all Glencore operations): Glencore’s Third Quarter 2026 Production Report states that own-sourced cobalt production was 13,700 tonnes for January–September 2026, down 52% from 28,500 tonnes a year earlier. Third-quarter output was 3,500 tonnes, 20% lower than the second quarter. Glencore attributes the decline to the DRC cobalt export quota regime and its focus on copper, with cobalt contained in mixed ore increasingly retained in solution rather than processed into saleable hydroxide.
DRC figures (secondary reporting of the mine tables): Kamoto Copper Company (KCC) produced 11,600 tonnes of cobalt in the first nine months, down 34% year on year, while Mutanda reported no cobalt output against 8,800 tonnes in the same period of 2025 — a combined DRC cobalt decline of about 56%. Copper moved the other way: KCC and Mutanda together produced 210,600 tonnes in the nine months, up 37% (KCC 158,900 tonnes, up 35%; Mutanda 51,700 tonnes, up 44%), reflecting more ore mined and improved grades.
Sources
Afrimet implications (analysis/inference)
Copper growth at a major producer is a positive availability signal, but it does not make material available on the open market. Lower cobalt output, and cobalt retained in solution, point to fewer immediately saleable hydroxide tonnes — and to possible future inventory release if policy permits.
For both metals, counterparties should be asked for product-specific allocation, current production and saleable inventory rather than headline mine output, together with confirmation of quotas, export permissions and any domestic processing obligations. Forward cobalt commitments should not be offered without a confirmed allocation behind them.
3. DRC lithium — KoBold survey clearance remains pending
Confirmed facts — as reported by the Financial Times, 30 October 2026
The Financial Times reported that KoBold Metals is seeking a UN Security Council sanctions-committee exemption so that a contractor can import and use an airborne tensor gravity gradiometer for a US$50 million DRC lithium exploration programme. Because the equipment is dual-use, it requires an exemption under the DRC arms embargo. The US State Department has submitted a request, which had not been approved at the time of reporting. KoBold says missing the dry-season survey window could delay the work by about a year.
KoBold’s suggestion that China may be obstructing approval is an allegation. China has denied it, and no evidence confirms interference. KoBold holds 14 DRC exploration licences; these are exploration licences, not a proven resource or a mining licence.
Afrimet implications (analysis/inference)
DRC lithium remains early-stage and sensitive to geopolitics and permitting; it should not be marketed as near-term supply, reserve or resource. Partnership conversations should be exploration-risk aware and milestone-based, distinguishing clearly between licence tenure, survey permission, discovery, resource estimate, feasibility, mining licence and offtake.
4. South Africa gold — illegal supply-chain risk; no new mine regulation
Confirmed facts — reported 30 October 2026
The Guardian described growing illegal gold activity around Johannesburg and its abandoned shafts, with police operations struggling to contain it. The report recalls that the mining minister cited 6,100 derelict and ownerless mines and 1,170 unsafe mine openings in 2025 — figures that are not new this week — and highlights unresolved closure, rehabilitation, safety and criminal-network issues.
The report does not describe a new law or a new official production estimate.
Sources
Afrimet implications (analysis/inference)
Gold’s high value and portability make origin and custody checks central to any transaction. Afrimet would require evidence of:
- Mining or trading rights and written seller authority.
- Production records and documented transport.
- Tax and royalty payments.
- Independent assay and an unbroken chain of custody.
- No purchases from undocumented intermediaries or abandoned-mine sources.
5. Market prices and supply signals
Confirmed facts — 30 October 2026 market reports; not live quotes
Gold: Reuters reported that spot gold fell 3.5% on 30 October to US$3,880.97 an ounce by 1813 GMT, its lowest level in about a year, amid a technology-equity selloff and liquidity selling, higher oil, inflation data and interest-rate expectations.
Copper: in early Friday trade, Reuters reported LME three-month copper at US$14,320.50 a tonne by 0310 GMT, set for a little-changed week. Its later report put three-month copper at US$14,140 by 1720 GMT and on track for a 1.8% decline in October, while noting that the LME cash premium over three-month copper (backwardation) remained elevated — a sign of nearby tightness despite monthly price pressure.
Cobalt: no new DRC weekly official export-reference sheet for 26 October–1 November was verified. Afrimet does not quote stale reference prices or treat LME cobalt metal as a proxy for DRC cobalt hydroxide; the week’s supply evidence is the Glencore report above.
Lithium: no new DRC or South African spot benchmark or mine offtake price was verified this week.
Sources
Afrimet implications (analysis/inference)
A fast gold correction argues for shorter quotation validity and clearly defined pricing references. For copper, elevated backwardation alongside a softer outright price means the benchmark, quotational period and any prompt-delivery premium should be fixed in writing. None of these figures is an executable price or an Afrimet quotation.
6. South Africa and DRC regulatory and project scan
Confirmed facts — no qualifying change verified, 26 October–1 November 2026
- South Africa: no new enacted mineral-specific gold, copper, cobalt or lithium law, royalty change, project final investment decision or binding offtake was verified. The non-binding Springbok lithium offers of 20 October fall outside this week and are not repeated.
- DRC: no new cobalt quota rule or mining-code or royalty amendment was verified; the notable changes were the administrative enforcement and trading-centre operations described above.
- No consequential new South African copper or cobalt project, or DRC or South African gold investment or offtake agreement, was verified.
Afrimet implications (analysis/inference)
With no formal rule change this week, the practical risk sits in enforcement and operations: who may sell, where, and on what documents. Existing quota and export requirements should continue to be confirmed transaction by transaction.
Afrimet desk priorities
Afrimet analysis — recommendations, not executed transactions
- Build a document-led diligence checklist for any artisanal copper-cobalt pathway, and monitor whether Musompo operates reliably.
- Seek only confirmed cathode or hydroxide allocations supported by assay and export rights.
- Keep DRC lithium at the exploration and partner-intelligence stage.
- Tighten gold chain-of-custody requirements.
- Shorten gold quotation validity and define the copper pricing benchmark and quotational period.
Discuss a verified mineral supply or partnership
Buyers, financiers and logistics partners assessing DRC or South African copper, cobalt, gold or lithium can contact the Afrimet trade desk or write to Trade@afrimetglobal.com. Every enquiry remains subject to verification, due diligence, documentation, contract and applicable law.
Disclaimer: this brief is market intelligence, not investment, legal or trading advice. Source data may be provisional, and transaction terms differ.